

Key Points at a Glance
- Definition & Goal: Structured investment controlling plans, manages, and monitors all investments throughout their entire lifecycle to avoid poor decisions and ensure long-term corporate success.
- Three Core Phases: A successful investment process comprises strategic investment planning, operational implementation, and rigorous post-investment review.
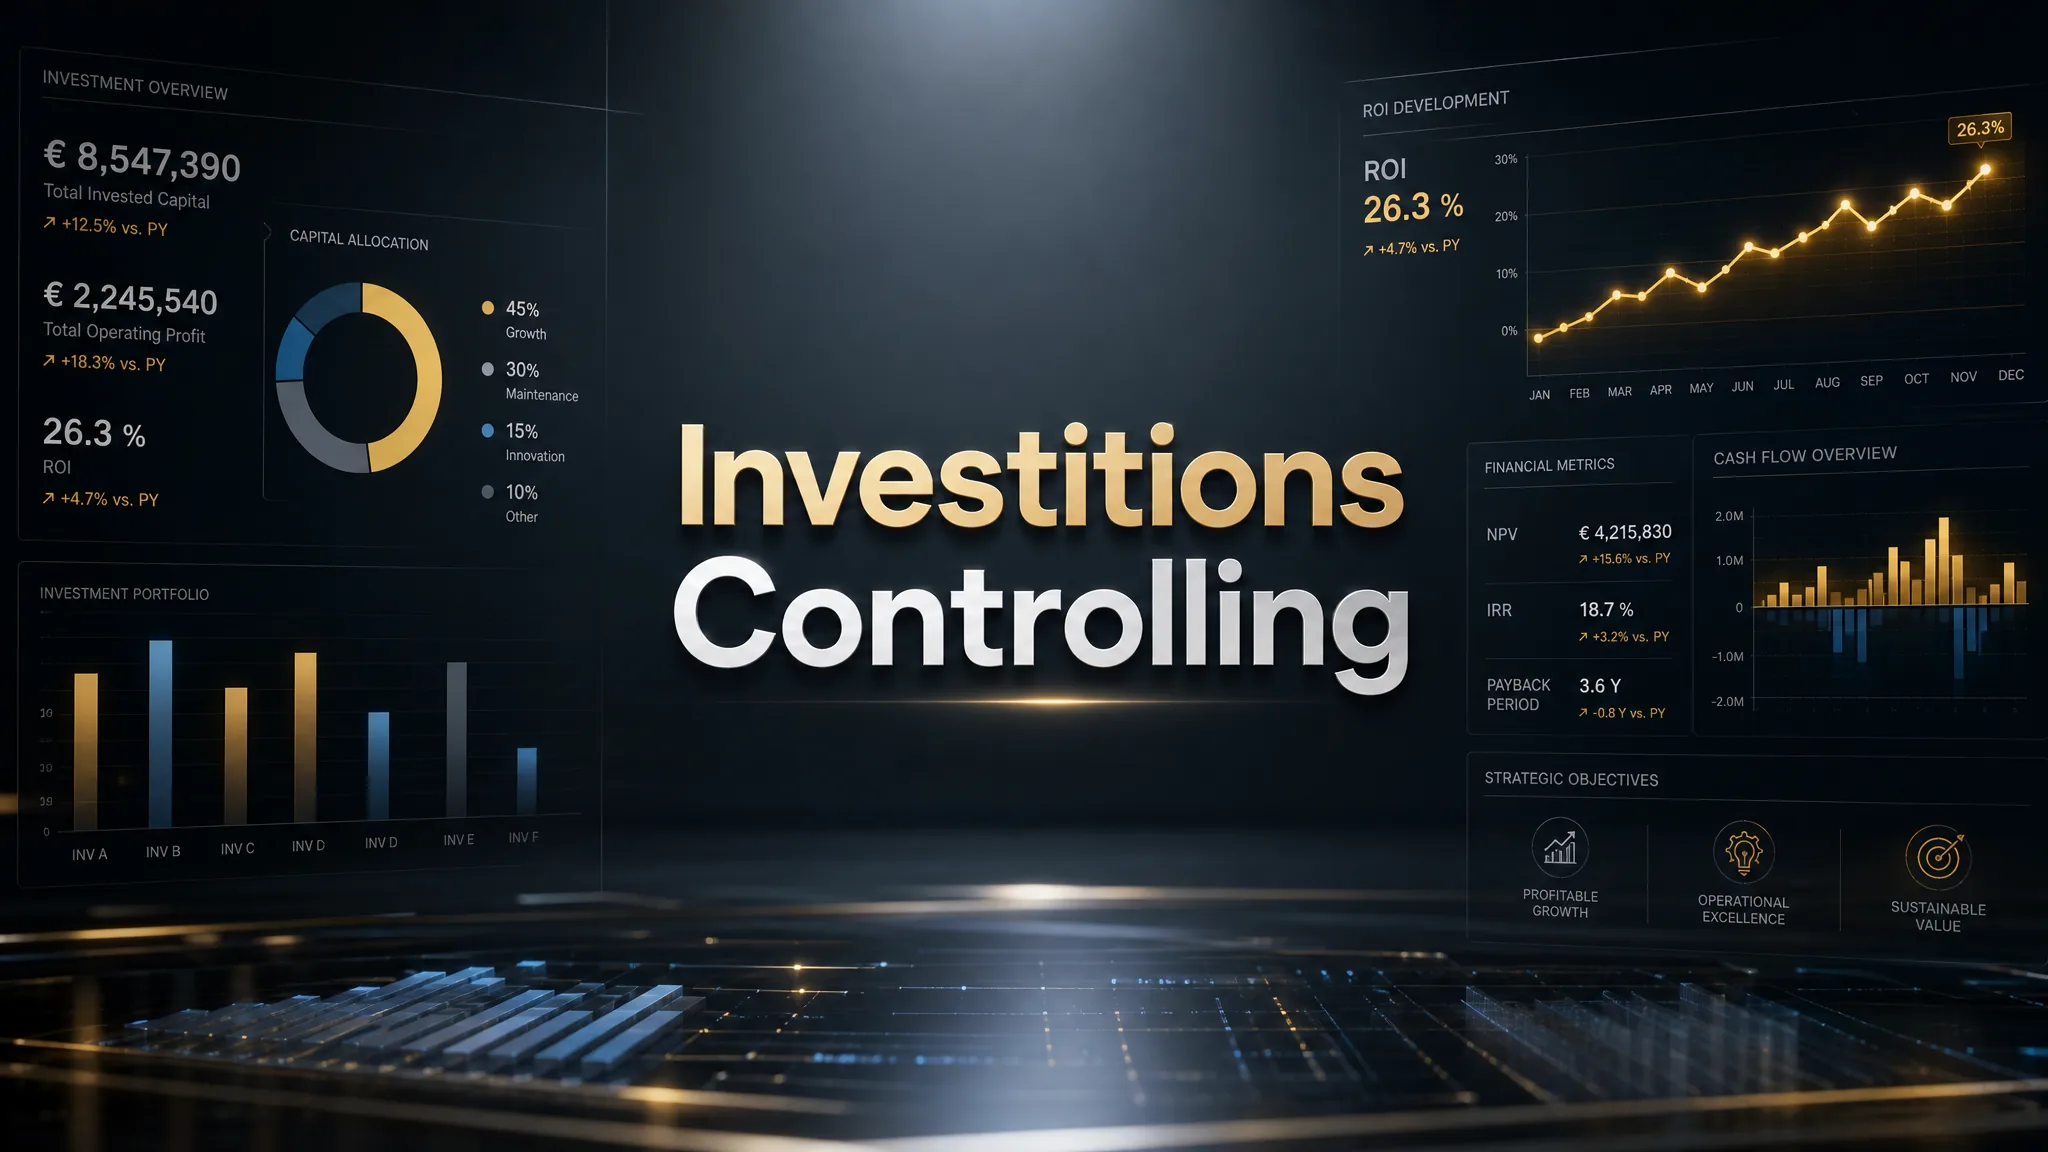
- Sound Methodologies: In addition to static methods, dynamic approaches—such as Net Present Value (NPV) and Internal Rate of Return (IRR)—provide reliable data by accounting for the time value of money.
- Data as a Success Factor: Seamless data integration and modern controlling software create transparency, reduce complexity, and form the foundation for future-proof investment decisions.
Distinction from Operational, Project, and Asset Controlling
Investment controlling is a key component of corporate controlling. While operational controlling primarily manages short- to medium-term earnings positions and ongoing budgets, investment controlling focuses specifically on long-term capital commitments. This article outlines how the entire investment process—from the initial idea and investment appraisal to project completion—is systematically supported.
A precise distinction from related disciplines is essential in practice: Project controlling monitors schedules, costs, and quality standards within the scope of operational projects. Asset controlling focuses on the accounting administration and balance-sheet reporting of assets that have already been capitalized. Investment controlling acts as a bridge: it evaluates economic viability prior to acquisition and ensures sustainable management throughout the asset’s entire useful life.
Why Tangible and Financial Assets Require Systematic Management
Long-term investments tie up significant financial resources and determine a company’s future growth. Poor decisions in this area are difficult to rectify after the fact; they strain liquidity, weaken the balance sheet, and limit strategic flexibility.
Whether tangible assets—such as buildings and machinery—or financial holdings (financial assets) are involved, every project entails specific risks. Professional investment management creates the transparency needed to objectively compare various investment options. The primary goal is to allocate available resources where they make the greatest contribution to corporate success.
Stages of the Investment Process: From Planning to Post-Investment Review
Phase 1 – Strategic Investment Planning and Budgeting
Investment planning lays the foundation for successful capital investments. During this initial phase, potential investment alternatives are gathered, aligned with strategic corporate goals, and assessed for feasibility. Sound budgeting ensures that planned investment projects do not exceed the established overall budget.
During the prioritization process, management compares all available options. It is necessary to evaluate which measures will facilitate entry into new markets or enhance operational efficiency. A valid assessment relies on realistic market data and precise assumptions regarding future cash flows.
Phase 2 – Implementation and ongoing project controlling
Once approval is granted, the implementation of the investment projects begins. This phase focuses on the continuous monitoring of project progress and costs. The investment controlling function works closely with project controlling to identify discrepancies between planned and actual figures at an early stage.
Regular comparisons of planned versus actual figures provide the management team with reliable data, enabling them to take corrective action in the event of unexpected bottlenecks or market shifts. This protects the available budget from uncontrolled overruns and ensures timely implementation.
Phase 3 – Post-implementation review as a driver of continuous improvement
A final post-implementation review takes place after the project goes live. Although often neglected in practice, this aspect of controlling offers valuable learning opportunities for future decisions. It involves verifying whether the projected returns and earnings potential actually materialized.
The post-implementation review uncovers the causes of any variances and establishes important benchmarks for future calculations. It thus serves as a key driver for the ongoing refinement of internal planning processes.
Typical KPIs for Data Quality
Share of fully maintained data records per category.
Percentage of correctly validated information.
Discrepancy rate between systems or sources.
Data within an acceptable update interval (e.g., < 30 days).
Utilization rate of provided data in operational processes.
Methods and Tools for Sound Investment Decisions
Static Methods: Quick but Methodologically Limited
Static investment appraisal methods are characterized by their ease of use. The most well-known techniques include cost, profit, profitability, and payback period calculations. They rely on average periodic figures and are ideally suited for an initial, rough assessment of smaller capital acquisitions.
The primary drawback of static approaches is that they disregard the time value of money. Compound interest effects and the timing of cash inflows are ignored; consequently, they should serve only as a supplementary tool for complex investment projects.
Dynamic Methods: Net Present Value (NPV) and Internal Rate of Return (IRR)
Dynamic tools take into account the precise timing of all cash flows over the entire useful life of the investment. The Net Present Value (NPV) method discounts all future revenues and expenses to their present value. If the NPV is greater than zero, the investment is considered advantageous.
The Internal Rate of Return (IRR) determines the calculated return on the invested capital. Both methods provide a mathematically precise basis for decision-making and enable an objective comparison of different investment alternatives.
Scenario Analysis and Risk Assessment for Future Investments
Since every forecast entails uncertainty, scenario analyses complement the range of available methods. By modeling various scenarios—such as best-case, realistic, and worst-case outcomes—it is possible to simulate the impact of market fluctuations on economic viability.
Management can identify at an early stage how sensitive a project is to rising procurement costs or declining demand. Such risk analyses significantly minimize the likelihood of unforeseen losses. Comparison of Static vs. Dynamic Evaluation Methods
A structural comparison of the methods is crucial for selecting the appropriate evaluation procedure. The following overview summarizes the strengths, weaknesses, and typical application areas of the most common evaluation methods:
| Evaluation Method | Typical Methods | Advantages | Disadvantages / Limitations |
|---|---|---|---|
| Static Methods | Cost comparison, profit comparison, payback period calculation | Simple to calculate, low data requirement, easy to understand. | Ignores the time value of money as well as the timing of cash flows. |
| Dynamic Methods | Net Present Value (NPV), Internal Rate of Return (IRR), Annuity method | Precise recording of all cash flows across the entire lifecycle. | Higher complexity and dependency on the chosen discount rate. |
| Risk Analyses | Scenario analyses, sensitivity analyses, Monte Carlo simulation | Transparent mapping of uncertainties and market fluctuations. | Requires valid baseline assumptions and reliable historical data. |
Typical Challenges in SME Investment Projects
Unrealistic Assumptions and the Risk of Poor Investments
Overly optimistic forecasts are among the most common causes of failed investment projects. Setting revenue expectations too high or underestimating start-up costs leads to distorted profitability calculations.
Investment controlling processes that lack a solid foundation run the risk of adopting such flawed assumptions without verification. Objective review mechanisms and standardized plausibility checks are essential to effectively minimize the risk of poor decision-making.
Avoiding Budget Overruns and Lack of Transparency
Without continuous monitoring during implementation, budget overruns can easily go unnoticed. Unclear responsibilities and a lack of reporting standards make it difficult for management to intervene in a timely manner.
Systematic milestone reviews provide a solution here. They ensure that cost trends are documented transparently and that any requests for additional funding undergo a rigorous approval process.
Fragmented Data Sources as a Barrier to Valid Assessment
In many SMEs, investment-related information is scattered across various systems or manual spreadsheets. This fragmentation slows down the decision-making process and increases the likelihood of errors.
A consistent data foundation is therefore the cornerstone of professional investment management. Investment decisions can only be made based on reliable figures if financial, procurement, and sales data flow together seamlessly.
How Modern Investment Controlling Benefits from Digitalization
Data Integration and Automated Reporting via Modern Software Solutions
Digitalization is fundamentally transforming investment controlling. Modern software solutions—such as Corporate Planner—and BI platforms like Qlik enable seamless integration with existing ERP systems. This makes relevant key performance indicators (KPIs) available in near real-time.
Manual, error-prone Excel calculations are replaced by automated workflows. This not only improves data quality but also frees up time for the controlling department to conduct strategic analyses.
Linking Investment Appraisal, Financing, and Liquidity
An integrated system directly links investment appraisal with the company’s financial and liquidity planning. This makes it possible to see—at the touch of a button—how a planned investment will impact future liquidity and capital requirements.
This provides decision-makers with a powerful set of tools to flexibly simulate investment opportunities and safeguard the organization’s financial stability at all times.
 Steer Investments Safely
Avoid bad investments, maximize ROI: Learn how to digitize your investment controlling and base capital decisions on a transparent, data-driven foundation.
Schedule a ConsultationFrequently Asked Questions About Investment Controlling
What distinguishes static from dynamic investment appraisal methods?
Static methods rely on average values from a single period and disregard the time value of money. In contrast, dynamic methods account for the precise timing of all cash flows over the entire useful life and discount them to a specific reference date.
How does investment controlling prevent poor decision-making within the company?
Through standardized evaluation processes, objective plausibility checks of projected figures, and the use of scenario analyses, investment controlling ensures that investment decisions are based on hard facts rather than gut feeling.
Which key performance indicators (KPIs) are most important for post-investment analysis?
For post-investment review, the primary focus is on variances between planned and actual acquisition costs, the achieved Return on Investment (ROI), and the deviation of realized cash flows from initial forecasts.